
Sometimes, a stock is so cheap you double-check the numbers three times.
Imagine this:
A company with 80% gross margins
45% net margins
35% return on equity
Zero debt
And over half a billion dollars in cash
And yet… it trades at just 3.5x EV/EBIT.
It gets even better: EV/net income? Just 2.1x.
Yes, that’s actual net income.
Still wondering which company this is?
The Setup
Let’s do the math:
Market cap: $891 million
Net cash: $507 million
→ Enterprise value: $384 million
2024 net income: ~$184 million
→ EV/net income = 2.1x
This isn’t a melting ice cube or a speculative story stock.
It’s a profitable, operationally efficient business — and the market is ignoring it.
So what’s going on?
What’s holding it back
Growth has slowed — and the market hates that.
Revenue dropped from $492 million in 2023 to $395 million in 2024.
2025? Flat. Q1 was already weak. Not the best start.
The U.S. market shrank from 65% down to 50%.
Economic pressure. Less demand from aesthetic clinics.
And then came new tariffs on Israeli-made products. That didn’t help margins.
Europe and Asia are doing okay — but not great.
They’re growing, but at lower profitability.
The result?
Falling sales. Shrinking margins. Nervous investors.
Which brings us to the company in question:
InMode (NASDAQ: INMD)
Maybe you’ve looked at it before. Maybe you moved on.
But at 2.1x net income? You might want to look again.
What’s under the hood
This isn’t just a cosmetic gadget play.
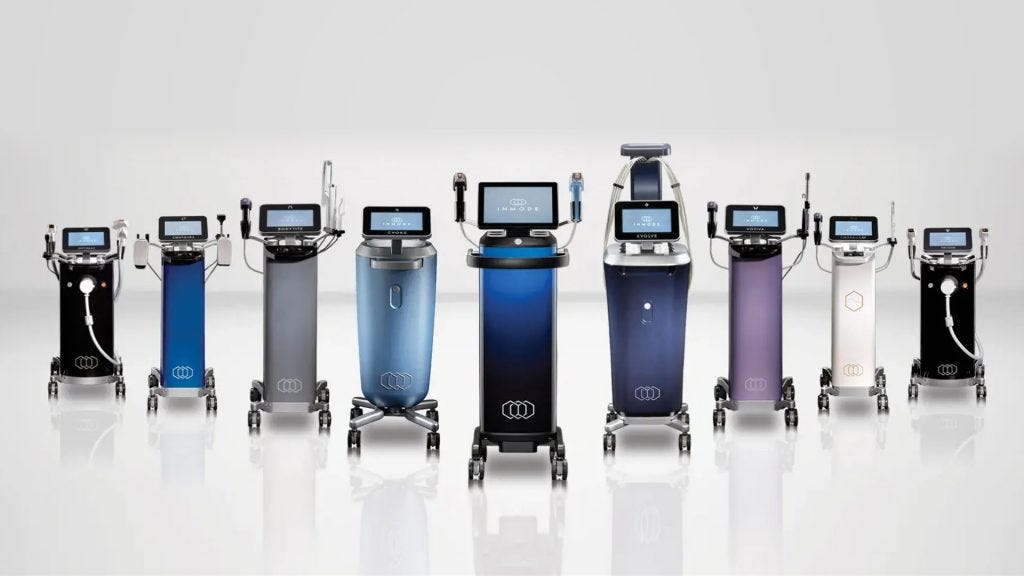
InMode sells RF-based medical devices used for things like skin tightening, fat reduction, and facial rejuvenation — high-margin, cash-pay procedures offered by plastic surgeons and dermatologists.
But they’re expanding into real medical markets too: incontinence, vaginal health, sleep apnea, erectile dysfunction, and more.
The first new platform could launch late 2025. Others will take longer and require FDA approval.
The idea? Combine aesthetic treatments with reimbursed clinical indications — and open up new revenue streams without giving up profitability.
And with $500M in cash and no debt, they’ve got the runway to make it happen.
Capital allocation? Aggressive.
InMode has already bought back 30% of its shares in the past two years — over $500 million returned to shareholders.
They may step it up again in 2026 (pending U.S. tax changes).
Or pursue M&A — prior deals didn’t happen because management wouldn’t overpay.
Activists are circling. Management is cautious but firm.
Why I’m buying
At 2.1x EV/net income, you don’t need a growth story.
You just need the business to stay alive. If growth comes back? That’s a bonus.
You're getting:
High margins
Strong balance sheet
A pipeline of optionality
Massive buybacks
And a valuation that doesn’t make sense
I hear you thinking: “There must be a catch.”
Sure — sentiment is weak. But the numbers don’t lie.
This is deep value. And it won’t stay that way forever.
Dig deeper,
Deep Value Stocks
Good find! Particularly now, after the MBO announcement, maybe that will wake the stock up.
however overall I'm a bit skeptical with buying even mispriced stocks that are declining in business performance as Buffett says "there is never just one roach in the kitchen".
Fantastic find.