
TUI AG is one of the largest tourism groups in the world: airlines, cruise ships, hotels, packaged holidays, destination experiences. This is not an asset-light website business. This is hard infrastructure scale.
And yet the stock trades like the recovery never happened.
This is exactly where deep value gets interesting: when the fundamentals already recovered… but the valuation is still stuck in the past.
The Business Isn’t Broken — The Market Narrative Is
After the pandemic, TUI had scars. Bailout. Dilution. Headlines. Everyone remembers that part of the story. But the punchline is this: that part is over. Today, the business is running normally. They are not fighting for survival anymore — they are optimizing for margin and profitable growth again.
Forward valuation:
~5.7x forward earnings
~5.4x forward FCF
~2.8x forward EV / EBITDA
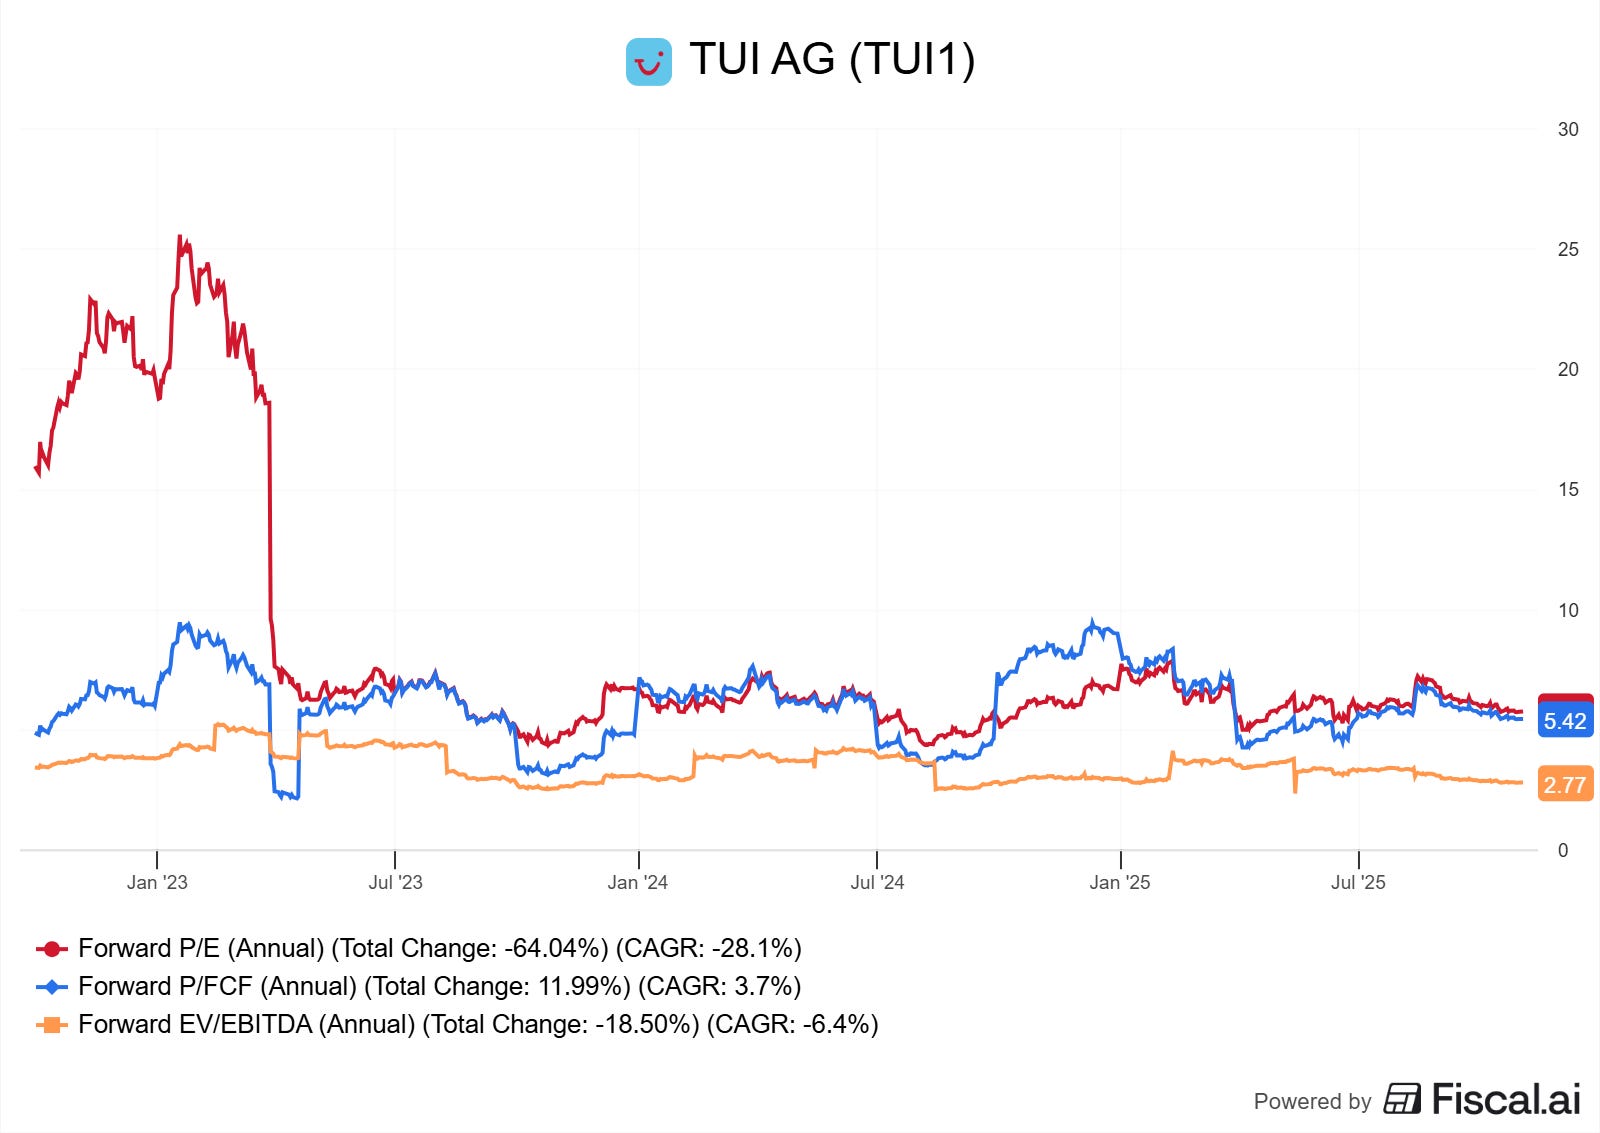
You normally see these multiples on companies close to liquidation or slow structural terminal decline.
Not on a global tourism machine that is printing profits and paying down debt.
That is the core irrationality here.
The Recovery Is Visible In The Numbers
Q2 2025 revenue: €3.7 billion (+1.5% YoY) despite Easter shifting into Q3.
Underlying EBIT: €207 million.
Management reaffirmed FY EBIT growth of 7-10%.
Across Europe, travelers are booking earlier, paying more, and prioritizing experiences. This is not “revenge travel hype” anymore. This is sticky behavior evolution. People are now structurally allocating a larger portion of discretionary money to travel.
Hotels are full. Cruises posted record revenue last summer. Airlines are running very high load factors with mid-90% ranges across key routes. This is not a small marginal bump. This is normalized demand + pricing power returning.
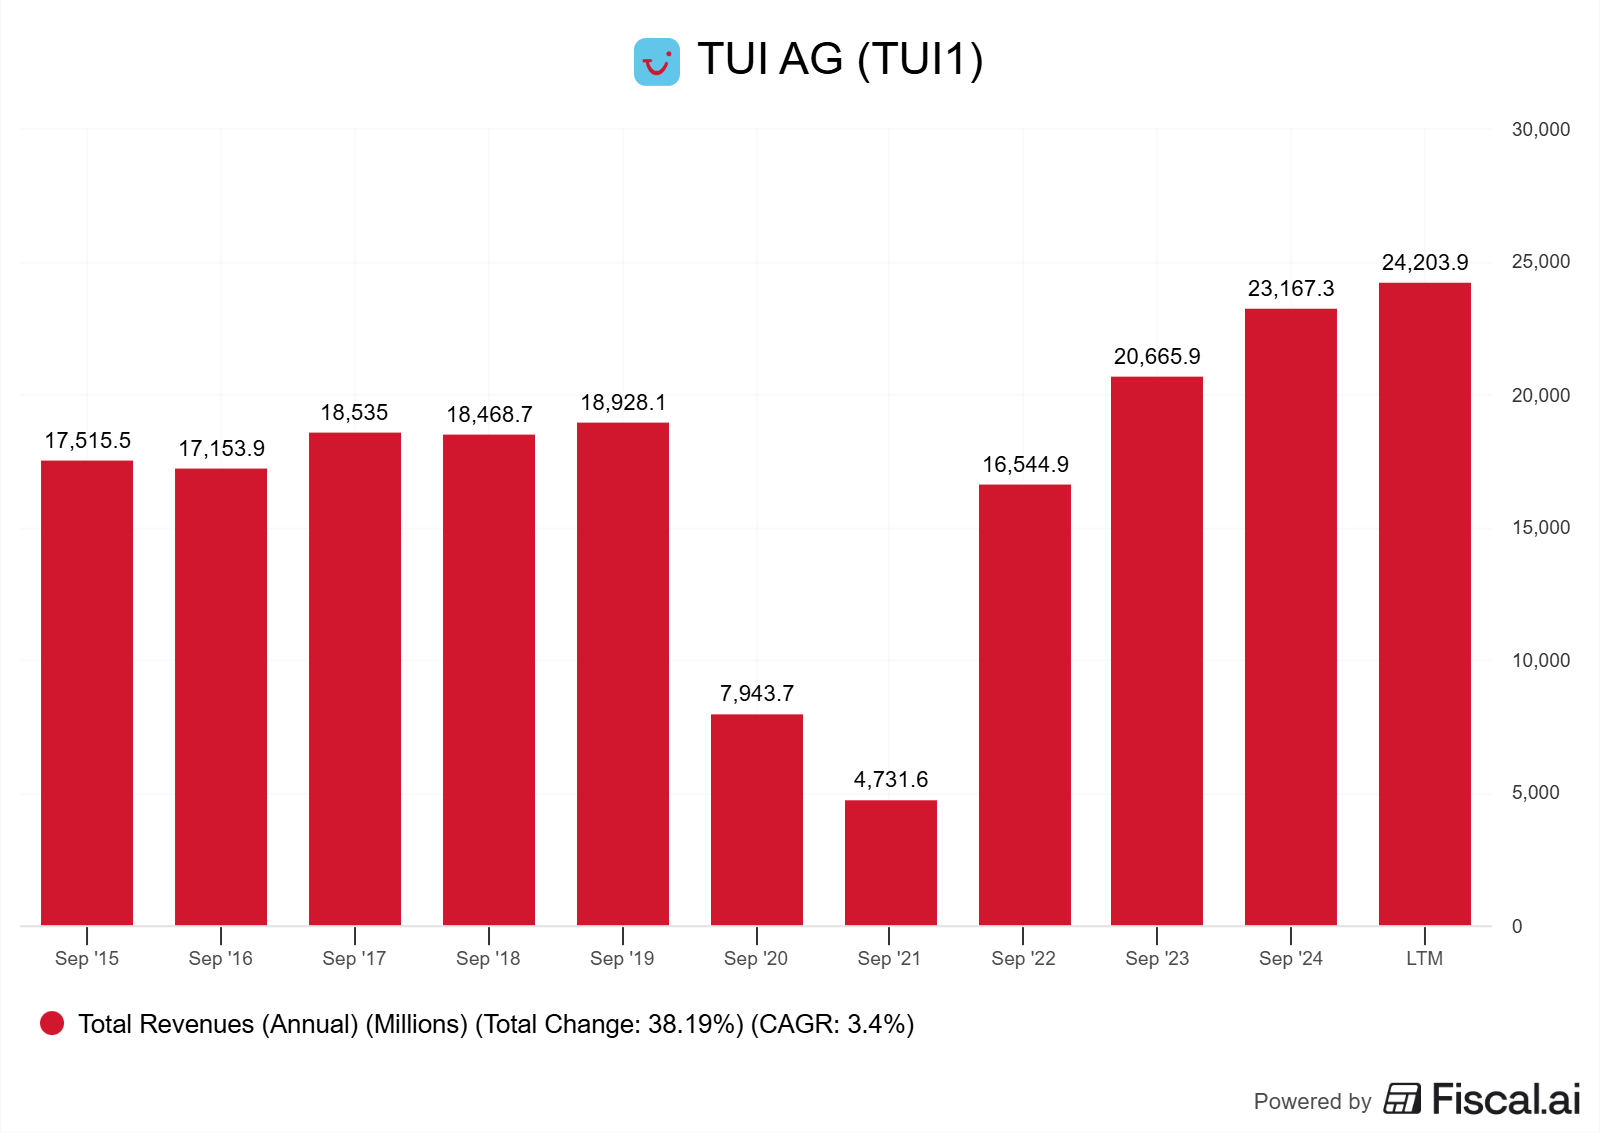
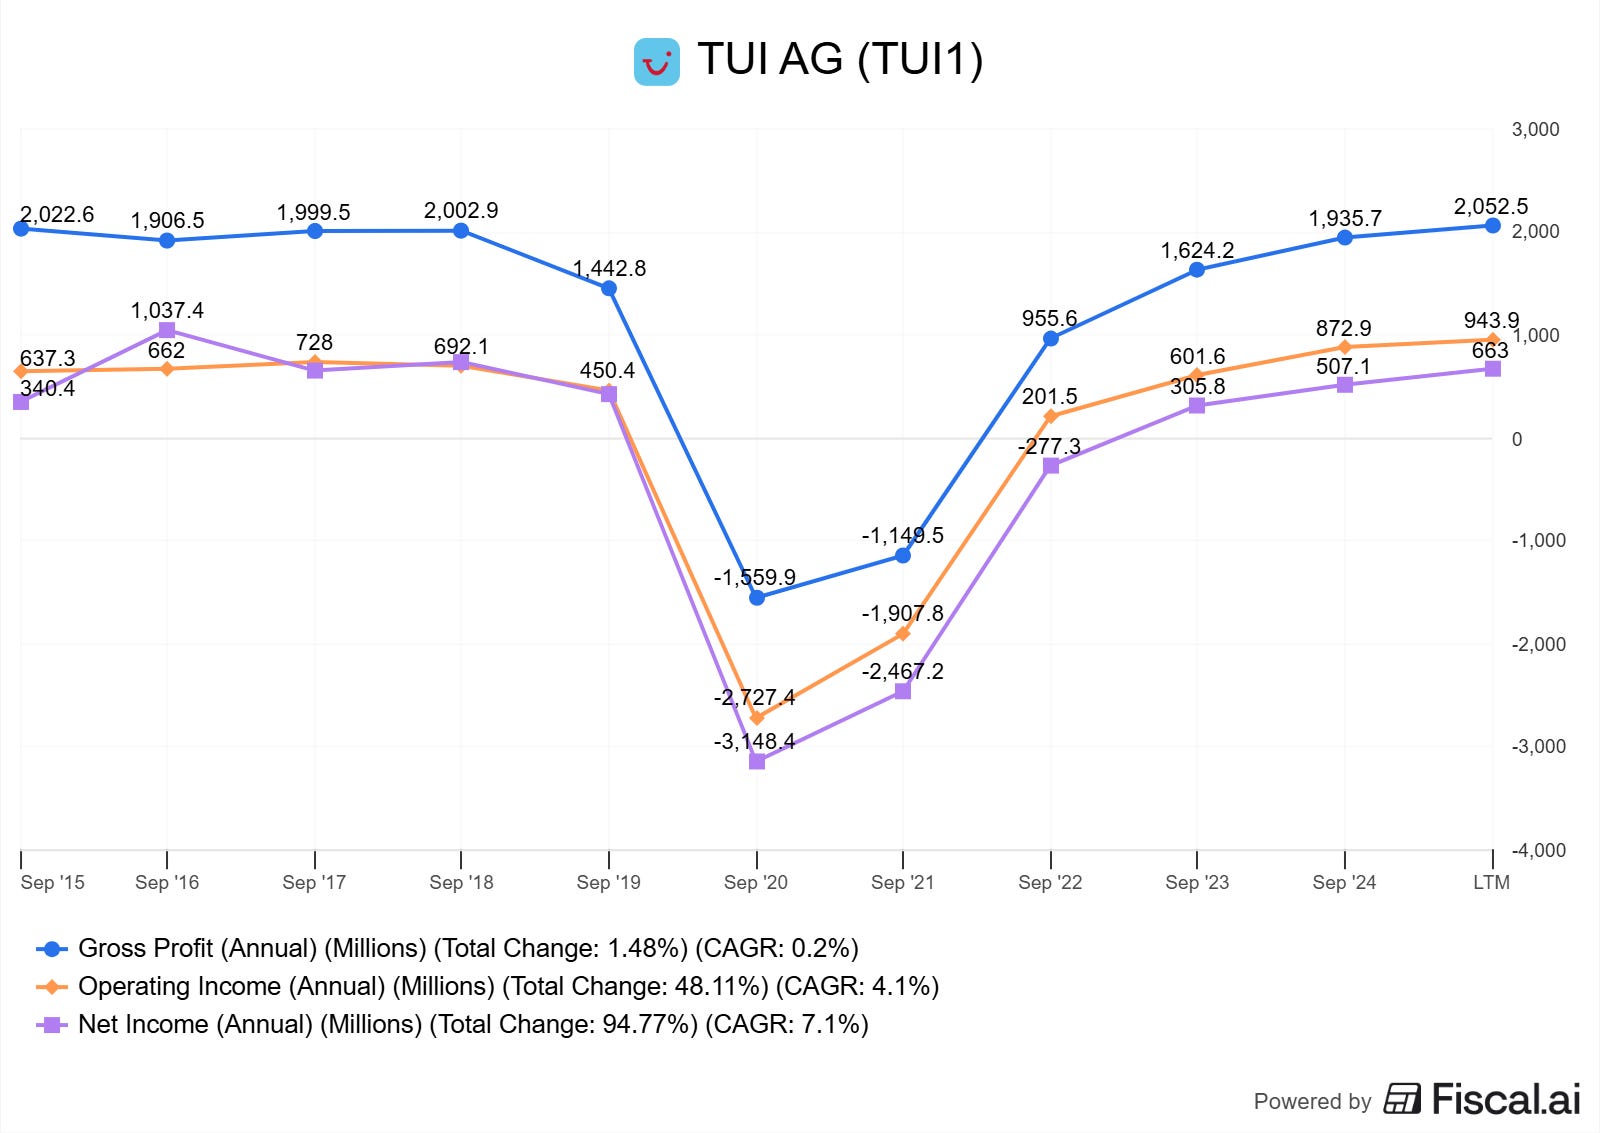
The operating model works again. Revenue has recovered and already surpassed the pre Covid levels.
Gross Profit and Operating Income have recoverd as well. Net Income is still lagging behind due to interest expenses. These interest expenses will decline as TUI is paying of its debts.
Why This Business Model Has More Embedded Quality Than Most Realize
TUI is not a middleman.
TUI owns supply.
That matters more than people think.
When travel demand rebounds, OTAs do not get margin leverage. TUI does. A hotel operator that fills more rooms with fixed costs covered expands margin significantly more than an OTA collecting 14% commission.
This is the hidden quality factor that screens miss.
On top of that:
Dynamic Packaging → capital-light ticket capture using 3rd party hotels/flights.
App funnel → lower CAC, higher attachment, direct & recurring.
Scale → bargaining power with suppliers + cost spread over massive volume.
The integrated structure + digital conversion is a flywheel.
The more volume flows through TUI’s system → the more value they capture per traveler.
The Market is Emotionally Mispricing This (classic behavioural deep value)
TUI is punished for its past.
Not for its present.
Investors are still anchored to rescue headlines. They remember TUI as “European tourism zombie bailout case.” Humans overweight pain. They overweight prior trauma. They underweight normalization.
Markets lag reality longer than people think.
This is why deep value works: not because analysts can forecast the future better — but because the market chronically misprices when narrative regime shifts have already happened on the ground.
Risks Exist — Of Course They Do — But They Are Already Embedded In Price
Travel is seasonal.
Fuel is volatile.
Europe macro is not risk-free.
Geopolitical shocks can hit out of nowhere.
Yes, that’s real.
But if this stock was 18x forward earnings → then these risks are thesis-breakers.
At under 6x earnings and under 3x EV/EBITDA → they are expected.
This is not “what if risk happens?”
This is “the market is already pricing that everything goes wrong forever.”
That’s the asymmetry.
What A Reasonable Re-Rating Could Look Like
If TUI simply goes back to normal sector range multiples, not premium luxury valuation — just boring base case normalization — the equity outcome changes meaningfully.
Moving from ~5.7x forward earnings to something closer to 10x is not aggressive. Sector comps support it. History supports it.
EV/EBITDA is even more extreme: ~2.8x vs sector norms ~6-8x.
This is not a growth stock thesis. This is a valuation normalization thesis.
TUI does not need to “crush it.”
It just needs to keep operating like it is right now.
Catalysts That Could Force The Market To Wake Up
official reinstatement of capital return (dividend or buyback) as debt drops further
continued expansion of dynamic packaging mix → structurally higher margin revenue
stronger app conversion → a cleaner LT investor narrative around recurring digital funnel
easing macro in Europe → discretionary demand steadies
more analyst coverage shifting off “bailout trauma lens” → narrative regime shift
None of these need to be heroic.
Just one or two is usually enough to kick the multiple into the right bracket.
Bottom Line
TUI is a global, asset-heavy travel empire with real structural advantages, improving margins, positive EBIT growth, strong demand, and normalized operations — still priced like a broken pandemic casualty.
Forward multiples under 6x earnings and under 3x EBITDA are not equilibrium valuation levels for a business performing like this. If travel demand remains fundamentally intact (which current data supports) and the company keeps executing normally — investors don’t need miracles for upside.
They just need the market to stop hallucinating disaster.
This travel giant is priced like a broken leftover.
It isn’t.
Deep Value Stocks