
Every now and then, you stumble on something that makes you stop and think: Wait... why is no one talking about this? How is this possible?
That’s exactly what happened when I came across this stock. This is one of those ultra-under-the-radar names that somehow slipped through the cracks — but not anymore.
Here’s the deal.
A Hidden Gem in the Lithium Triangle
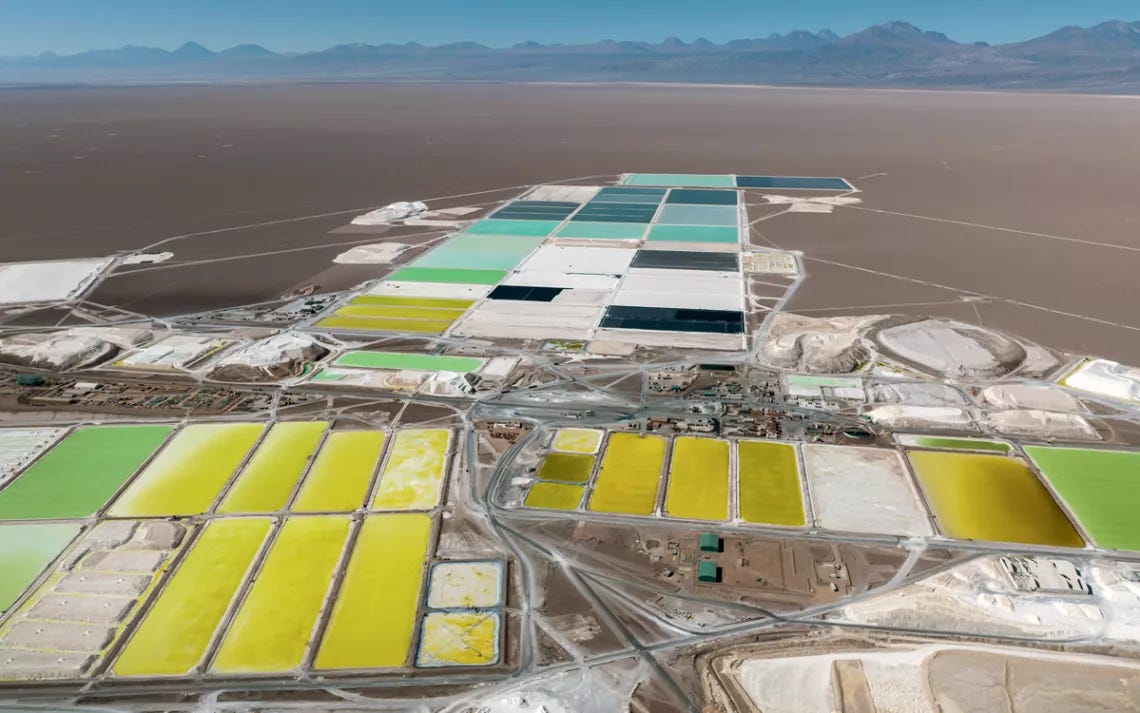
Lithium Chile (TSXV: LITH) is a small Canadian exploration company with lithium projects in Argentina and Chile. On April 9, 2025, they signed a binding letter of intent to sell 80% of their flagship asset — the Salar de Arizaro project — for $180 million.
To put that in perspective: the company’s entire market cap is only about $90 million.
Yes — they’re selling one asset for twice the value of the entire company.
I hear you thinking: “They must be drowning in debt.” But nope — Lithium Chile is debt-free and actually holds a net cash position of around $1 million.
And yet? Crickets.
A Massive Special Dividend?
If the deal goes through (pending final agreement, shareholder approval, and regulatory clearance), there's a very real chance shareholders could receive a special dividend of around C$0.50 per share — at a time when the stock is trading around C$0.60.
You read that right. That’s potentially 80% of your money back in cash, and you still own the rest of the company.
And here's what you still get to keep:
A 20% stake in Arizaro
89% ownership of an adjacent block (Block IV)
The Salar de Coipasa project in Chile (with a resource estimate of 3.7 million tonnes LCE)
12 other early-stage lithium projects
And potentially a significant cash position post-sale
According to some analysts, the Salar de Arazar project for which the company received a $180 million bid is not eve
n their most valuable project!
So Why the Discount?
Simple: the market doesn’t believe it yet.
The deal isn’t finalized, and lithium prices have been in the dumps lately. That’s keeping sentiment — and the stock price — depressed. Investors are waiting on certainty. But while they wait, the upside is staring us right in the face.
Another wildcard: the rumored buyer of the Arizaro stake is most likely Chinese. Canada has been increasingly protective of its critical minerals sector, especially when Chinese state-linked capital is involved. There’s a risk regulators block the deal.
But here’s the thing — there are workarounds. Lithium Chile could simply relocate its headquarters to avoid Canadian jurisdiction. That’s not theory — it’s been done before. And if the deal falls through? The company still owns a world-class asset it could develop or sell elsewhere.
My Thesis
This is a classic deep value setup. One project is worth more than the whole company. You're potentially getting a giant cash return plus ongoing upside in multiple high-quality lithium assets.
And no one’s paying attention.
I found this idea myself — not from a newsletter, not from a tip, just from digging through small-cap miners and looking where no one else was looking.
The best part? The market hasn't woken up yet. But it will.
Until then, this stock might just be the most overlooked lithium play out there.
Stay contrarian,
Deep Value Stocks